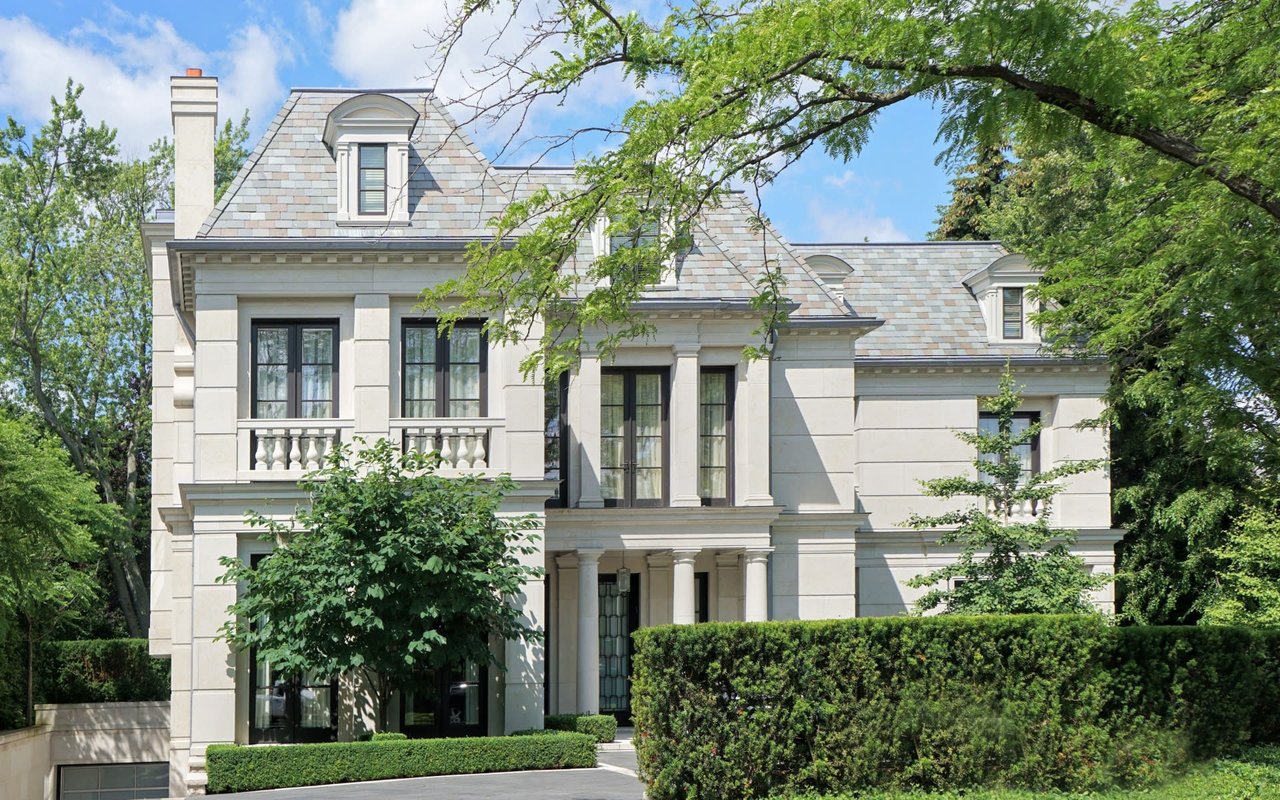
Buying a home in South Tampa’s 33629 ZIP code often means competing for distinctive properties, from established residences near Bayshore to larger homes on sought-after residential streets. For some buyers, traditional mortgage financing may not be the only path to ownership. Seller financing, sometimes called owner financing, can provide another structure—but it requires careful evaluation.
With more than 40 years of combined real estate experience, Emeri Lewkowicz and Joe Lewkowicz of The Lewkowicz Group understand that financing is not simply about getting a transaction to closing. It is about making sure the structure of the purchase fits the property, the buyer’s financial position, and the seller’s objectives.
“When we discuss seller financing with a buyer, we want them to understand exactly what they are agreeing to—not simply focus on whether the seller is willing to finance the purchase,” says the Lewkowicz Group approach.
How Does Seller Financing Work?
In a traditional purchase, a bank lends the buyer money and the buyer makes mortgage payments to the lender. With seller financing, the seller provides some or all of the financing, and the buyer makes payments to the seller under agreed-upon terms.
The arrangement can potentially involve negotiations over the purchase price, down payment, interest rate, repayment period, amortization, and whether there is a balloon payment.
For a 33629 buyer, Emeri and Joe recommend looking beyond the headline interest rate. The entire financing structure matters.
Why Might a 33629 Buyer Consider It?
Seller financing can sometimes be useful when a buyer's circumstances don't fit neatly into conventional lending criteria or when a seller has a reason to structure the sale differently.
It may also create an opportunity for buyers and sellers to negotiate terms directly rather than relying entirely on a conventional mortgage product.
However, seller financing is not automatically easier or less expensive than a traditional mortgage. The buyer still needs to understand the property's value, the financing terms, closing costs, taxes, insurance, and long-term payment obligations.
What Should Buyers Examine Carefully?
This is where local experience becomes particularly important.
First, understand the interest rate and payment structure. A lower initial payment can look attractive, but buyers should determine how much they will actually pay over the life of the agreement.
Second, pay close attention to balloon payments. If the agreement requires a large payment after a certain number of years, the buyer needs a realistic plan for refinancing or paying that amount.
Third, investigate the property's title and existing financing. A buyer should not assume that a seller can simply finance a property without considering existing liens or mortgages.
Fourth, have the documents professionally reviewed. Seller financing involves legal and financial obligations that go well beyond a standard purchase contract. Florida law also contains specific mortgage-lending and exemption provisions, while federal Regulation Z includes rules and exemptions applicable to certain seller-financing arrangements.
What About Sellers and Investors?
Seller financing can also be a strategic consideration for a 33629 seller or real estate investor. It may create an alternative way to structure a transaction, but the seller effectively becomes a creditor and takes on responsibilities and risks associated with receiving payments over time.
That's why Emeri and Joe encourage sellers to evaluate not only the sales price but also the buyer's ability to perform, the security supporting the financing, the repayment terms, and the seller's long-term financial objectives.
The South Tampa Perspective
In a market as established and varied as South Tampa, financing decisions should always be considered in the context of the individual property.
Emeri Lewkowicz and Joe Lewkowicz bring decades of combined experience helping buyers, sellers, and investors navigate Tampa real estate. Their local knowledge allows them to look beyond the transaction itself and help clients understand how price, property characteristics, financing structure, and long-term ownership goals fit together.
If you're considering a 33629 property with seller financing, start by understanding every term before signing. Seller financing can be a legitimate alternative to conventional financing, but the right questions—and the right professional guidance—are essential.